The operating partner behind private markets’ next chapter
02 Sep 2026
Alternatives have become more global, more complex, and more operationally needed. Centralis Group’s CEO Aidan Foley talks to Asset Servicing Times about how the firm is scaling — through capital markets expansion, a transatlantic platform, and disciplined investor-backed growth — while keeping its specialist, senior-led model intact
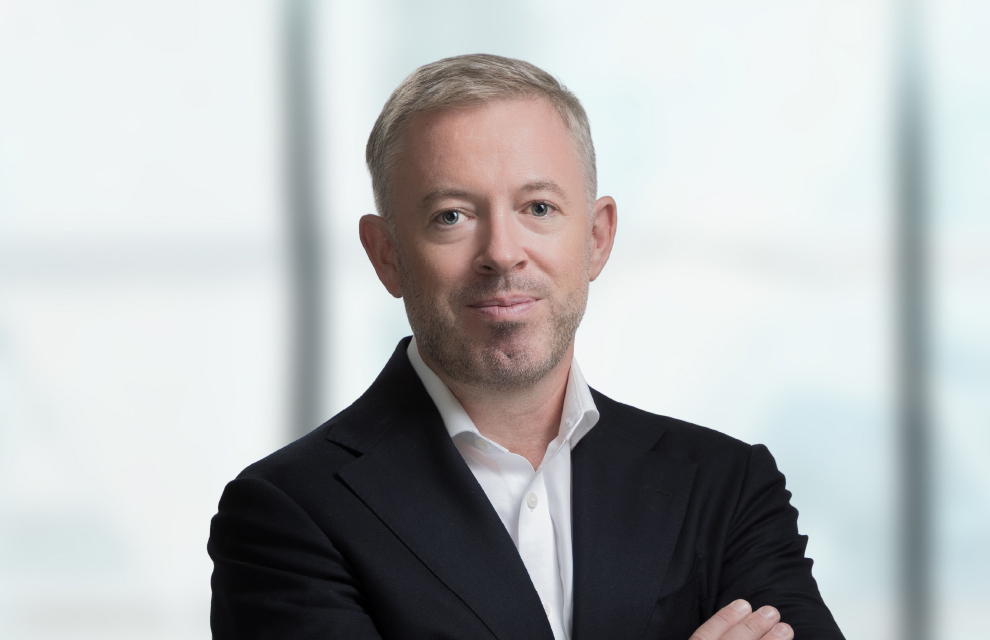 Image: Centralis Group
Ask any asset manager where their pain points lie; the answer is rarely front office. You will hear issues stemming from the back and middle — the servicing, the reporting, the governance — too much of the sector has failed to keep pace with clients. Managers are being served by providers assembled through a string of acquisitions that have not been properly integrated, as a result the client experience is served through legacy platforms that were never built for today’s cross-border complexity, delivering a commoditised service that is not modern-day tech-enabled. Meanwhile, funds have adopted more complex global structures against an evolving regulatory landscape. What used to be a periodic administrative task is now a continuous, cross-border discipline — the risk is shared between the managers, and appointed providers. Oversight or cutting corners results in steep operational costs, elevated risks, and a sharp fall in investor confidence.
At Centralis, we have built a business on combatting these pressure points, providing asset managers and multinational corporates with their most complex, cross-border, outsourced corporate, fund, and debt capital markets services — managed by senior industry experts, delivered accurately and on time. This is a deliberately narrow promise. We are not trying to be the largest administrator in the market; we are trying to be the one clients trust with their most critical and challenging work.
A common observation we see time and time again — a global alternative asset manager deploys capital through a web of cross-border special-purpose vehicles (SPVs) — real cash flows, multiple parties, waterfalls, and paydowns that must be right every time, across each currency. Forming the vehicles was the easy part and, frankly, a commodity. The value, and the risk, sat in administering the money moving through the structure accurately and reporting it cleanly to the manager and its investors.
This is our sweet spot, and precisely the work of a commoditised, legacy-platform model tends to underserve. It is a small example of a larger point: we treat complexity as our core competence, not as an exception to be priced away.
Growing intelligently, not swiftly
The more challenging operating environment raises the bar on the quality of growth. Our approach is disciplined: we expand where there is durable client demand, and where we can add genuine capability, jurisdictional strength, or access to higher-growth markets. Acquisitions must earn their place, and each new service line should follow the same discipline.
Two of those service lines illustrate the point — and both sit within a deliberate capital markets push that is complementary to an established fund services franchise across governance, risk and compliance (GRC), fund administration, and fund-linked SPVs. The logic is straightforward: the substance, structuring, and governance muscle we already apply for asset managers can be extended to more asset classes, without diluting the services providers exceed in.
Loan agency: Expert-led and tech-enabled from day one
Private credit continues to grow rapidly, and with it the demand for independent, conflict-free facility agents, and security trustee services. Increasingly, lenders and sponsors want an independent, non-bank agent they can trust with the cash and the controls — these are appointments driven by the law firms and arrangers structuring the deals. We have launched a dedicated loan agency capability to meet that demand — and we have done it in a way that reflects how we think a new service line should be built.
We start with two differentiators most new entrants struggle to claim together.
First, expertise: the offering is led by Joe Ellis-Grewal, CFA, based in our Central London office, an experienced key figure across the UK loan agency and administration market with a strong record across credit products.
Second, technology: we are launching as fully tech-enabled from day one with the utilisation of a market leading, modern, cloud-based loan servicing platform, rather than the legacy outdated systems many incumbents are still trying to escape. Most newcomers have people or technology. We have chosen to launch with both.
Aviation finance: A clear expansion signal
Aviation finance is our second capital markets expansion, and a firm signal of intent rather than a tentative toe in the water. The logic is the same. Ireland sits at the centre of global aircraft leasing and a fast-growing aviation asset-backed securities (ABS) market, Centralis already has both the Irish base and a long-standing strength in the SPV services that lessors, airlines, banks, and asset managers rely on. Building a dedicated aviation finance capability is a natural, complementary extension of the same platform — entered, as with loan agency, led by specialists with the operational discipline our clients expect.
An independent partner to the advisory community
How we work matters as much as what we do, we operate as an independent partner to the legal and advisory community, not a competitor.
Law firms, fund counsel, and arrangers structure and advise; we administer, report, and govern once the structure is live. Clients are comfortable putting us in front of their boards and their investors because we are not trying to own the end-relationship — the adviser who introduces us has reassurance that they own the relationship.
This independence should be viewed as paramount and commercially valuable to everyone in the chain. It is why a growing share of our most crucial mandates come through people who already know our work. Counsel and intermediaries who trust us with the operational delivery are free to focus on advising and structuring. In a market rightly sensitive to conflicts, being the safe, independent pair of hands is not a soft attribute. It is a hard differentiator we see overlooked by the need for commercial gain.
A transatlantic platform for global managers
The most visible expression of our strategy is our acquisition of PINE Advisor Solutions, the US fund governance, compliance, and distribution business headquartered in Denver. PINE gives Centralis an immediate and credible US front end — an established, trusted presence with direct access to fund boards, and advisers across high growth segments: registered funds, evergreen and interval structures, active ETFs, and outsourced private-fund chief financial officer (CFO) services. PINE Distributors, which is an affiliated broker dealer, recently surpassed US$45 billion in assets under distribution, a marker of the scale and trust built.
Strategically, PINE creates two connected ‘power alleys’. In Europe, Centralis provides substance-and-complexity structuring through SPV services and fund governance, risk, and compliance (GRC). In the US, PINE provides fund governance and regulatory services. Together they form a single, multi-jurisdictional platform for alternative managers who need consistent governance, operational discipline, and regulatory support across both sides of the Atlantic from a single partner.
As part of our long-term strategy — this is a widening of our existing GRC lane, not a new strategic tangent. It extends the GRC footprint we have built in the UK and Cayman into the US, and it is highly complementary to our UK GRC business.
It is a natural next step in a deliberate transatlantic build — and clients will continue to work with the teams they know and trust, now backed by the scale and reach of an international platform.
A platform with long-term backing
None of this happens without the support of conviction and capital. Our majority shareholder, HGGC, backed Centralis because it saw a strong specialist business with genuine client trust, sector relevance, and clear expansion plans.
Their investment represents a long-term ownership stake, not a short-term capital deployment.
The relationship is built on a simple division of roles. HGGC backs the long-term strategy and helps us invest in the systems, people, and service quality that sustained growth demands.
Management remains the voice of the business and the custodian of the client relationships. The PINE acquisition is the clearest proof of that model working in practice: capability-additive, disciplined M&A into a higher-growth market, executed by the management team and, supported by our investor.
What lies ahead
My conviction is that the winners in fund and corporate services over the next decade will not be the largest processors.
They will be the integrated, cross-border, governance-led specialists who can operate wherever their clients invest and treat complexity as their core competence rather than an exception to be priced away.
Equally, we are not trying to be everything to everyone. We would rather specialise where we have a right to win and excel, than spread ourselves too thinly across services we cannot lead. Every expansion we make — loan agency, aviation finance, the US platform — is chosen on that test: a market where our expertise, our clients and our capabilities give us collateral to compete, and win.
The foundations and future of any reputable service provider should follow: complete, bespoke expertise across corporate, fund, and debt capital markets services for asset managers and multinational corporates, delivered by senior people who own the outcome.
As alternatives and the capital markets that serve them enter their next phase — more global, more complex, more demanding — our ambition is to be the operating partner behind it.
At Centralis, we have built a business on combatting these pressure points, providing asset managers and multinational corporates with their most complex, cross-border, outsourced corporate, fund, and debt capital markets services — managed by senior industry experts, delivered accurately and on time. This is a deliberately narrow promise. We are not trying to be the largest administrator in the market; we are trying to be the one clients trust with their most critical and challenging work.
A common observation we see time and time again — a global alternative asset manager deploys capital through a web of cross-border special-purpose vehicles (SPVs) — real cash flows, multiple parties, waterfalls, and paydowns that must be right every time, across each currency. Forming the vehicles was the easy part and, frankly, a commodity. The value, and the risk, sat in administering the money moving through the structure accurately and reporting it cleanly to the manager and its investors.
This is our sweet spot, and precisely the work of a commoditised, legacy-platform model tends to underserve. It is a small example of a larger point: we treat complexity as our core competence, not as an exception to be priced away.
Growing intelligently, not swiftly
The more challenging operating environment raises the bar on the quality of growth. Our approach is disciplined: we expand where there is durable client demand, and where we can add genuine capability, jurisdictional strength, or access to higher-growth markets. Acquisitions must earn their place, and each new service line should follow the same discipline.
Two of those service lines illustrate the point — and both sit within a deliberate capital markets push that is complementary to an established fund services franchise across governance, risk and compliance (GRC), fund administration, and fund-linked SPVs. The logic is straightforward: the substance, structuring, and governance muscle we already apply for asset managers can be extended to more asset classes, without diluting the services providers exceed in.
Loan agency: Expert-led and tech-enabled from day one
Private credit continues to grow rapidly, and with it the demand for independent, conflict-free facility agents, and security trustee services. Increasingly, lenders and sponsors want an independent, non-bank agent they can trust with the cash and the controls — these are appointments driven by the law firms and arrangers structuring the deals. We have launched a dedicated loan agency capability to meet that demand — and we have done it in a way that reflects how we think a new service line should be built.
We start with two differentiators most new entrants struggle to claim together.
First, expertise: the offering is led by Joe Ellis-Grewal, CFA, based in our Central London office, an experienced key figure across the UK loan agency and administration market with a strong record across credit products.
Second, technology: we are launching as fully tech-enabled from day one with the utilisation of a market leading, modern, cloud-based loan servicing platform, rather than the legacy outdated systems many incumbents are still trying to escape. Most newcomers have people or technology. We have chosen to launch with both.
Aviation finance: A clear expansion signal
Aviation finance is our second capital markets expansion, and a firm signal of intent rather than a tentative toe in the water. The logic is the same. Ireland sits at the centre of global aircraft leasing and a fast-growing aviation asset-backed securities (ABS) market, Centralis already has both the Irish base and a long-standing strength in the SPV services that lessors, airlines, banks, and asset managers rely on. Building a dedicated aviation finance capability is a natural, complementary extension of the same platform — entered, as with loan agency, led by specialists with the operational discipline our clients expect.
An independent partner to the advisory community
How we work matters as much as what we do, we operate as an independent partner to the legal and advisory community, not a competitor.
Law firms, fund counsel, and arrangers structure and advise; we administer, report, and govern once the structure is live. Clients are comfortable putting us in front of their boards and their investors because we are not trying to own the end-relationship — the adviser who introduces us has reassurance that they own the relationship.
This independence should be viewed as paramount and commercially valuable to everyone in the chain. It is why a growing share of our most crucial mandates come through people who already know our work. Counsel and intermediaries who trust us with the operational delivery are free to focus on advising and structuring. In a market rightly sensitive to conflicts, being the safe, independent pair of hands is not a soft attribute. It is a hard differentiator we see overlooked by the need for commercial gain.
A transatlantic platform for global managers
The most visible expression of our strategy is our acquisition of PINE Advisor Solutions, the US fund governance, compliance, and distribution business headquartered in Denver. PINE gives Centralis an immediate and credible US front end — an established, trusted presence with direct access to fund boards, and advisers across high growth segments: registered funds, evergreen and interval structures, active ETFs, and outsourced private-fund chief financial officer (CFO) services. PINE Distributors, which is an affiliated broker dealer, recently surpassed US$45 billion in assets under distribution, a marker of the scale and trust built.
Strategically, PINE creates two connected ‘power alleys’. In Europe, Centralis provides substance-and-complexity structuring through SPV services and fund governance, risk, and compliance (GRC). In the US, PINE provides fund governance and regulatory services. Together they form a single, multi-jurisdictional platform for alternative managers who need consistent governance, operational discipline, and regulatory support across both sides of the Atlantic from a single partner.
As part of our long-term strategy — this is a widening of our existing GRC lane, not a new strategic tangent. It extends the GRC footprint we have built in the UK and Cayman into the US, and it is highly complementary to our UK GRC business.
It is a natural next step in a deliberate transatlantic build — and clients will continue to work with the teams they know and trust, now backed by the scale and reach of an international platform.
A platform with long-term backing
None of this happens without the support of conviction and capital. Our majority shareholder, HGGC, backed Centralis because it saw a strong specialist business with genuine client trust, sector relevance, and clear expansion plans.
Their investment represents a long-term ownership stake, not a short-term capital deployment.
The relationship is built on a simple division of roles. HGGC backs the long-term strategy and helps us invest in the systems, people, and service quality that sustained growth demands.
Management remains the voice of the business and the custodian of the client relationships. The PINE acquisition is the clearest proof of that model working in practice: capability-additive, disciplined M&A into a higher-growth market, executed by the management team and, supported by our investor.
What lies ahead
My conviction is that the winners in fund and corporate services over the next decade will not be the largest processors.
They will be the integrated, cross-border, governance-led specialists who can operate wherever their clients invest and treat complexity as their core competence rather than an exception to be priced away.
Equally, we are not trying to be everything to everyone. We would rather specialise where we have a right to win and excel, than spread ourselves too thinly across services we cannot lead. Every expansion we make — loan agency, aviation finance, the US platform — is chosen on that test: a market where our expertise, our clients and our capabilities give us collateral to compete, and win.
The foundations and future of any reputable service provider should follow: complete, bespoke expertise across corporate, fund, and debt capital markets services for asset managers and multinational corporates, delivered by senior people who own the outcome.
As alternatives and the capital markets that serve them enter their next phase — more global, more complex, more demanding — our ambition is to be the operating partner behind it.
NO FEE, NO RISK
100% ON RETURNS If you invest in only one asset servicing news source this year, make sure it is your free subscription to Asset Servicing Times
100% ON RETURNS If you invest in only one asset servicing news source this year, make sure it is your free subscription to Asset Servicing Times