
Bhutan builds beyond Bitcoin
30 Sep 2026
Zarah Choudhary explores how Bhutan is moving beyond sovereign Bitcoin mining to build the regulatory, custody, and market infrastructure with insights from Gracy Chen, CEO of Bitget
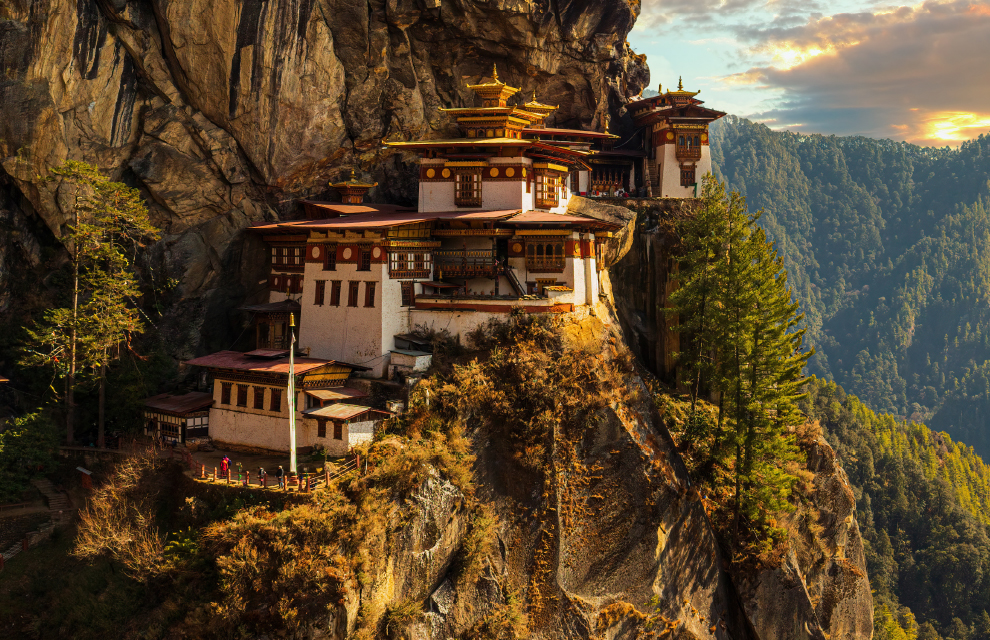 Image: thimphu/stock.adobe.com
From mining to market infrastructure
Bhutan’s digital asset story began with mining. It is now becoming a story about market infrastructure. The Himalayan kingdom has used surplus hydropower to mine Bitcoin through state-owned investment arm Druk Holding and Investments (DHI), converting renewable energy into a sovereign digital asset position.
Reuters reported in 2025 that DHI had been investing in cryptocurrencies since 2019, with proceeds supporting government expenditure and providing access to foreign-currency liquidity.
Rather than approaching digital assets first through private-sector trading, Bhutan developed exposure at the sovereign level. The next phase, centred on Gelephu Mindfulness City (GMC), is focused on whether that experience can be translated into a regulated financial services ecosystem capable of supporting institutional capital. Gracy Chen, CEO of Bitget, says this is the more important development.
“Bhutan’s experience with Bitcoin gave it an unusually early understanding of digital assets at the sovereign level. The next step of turning that experience into financial infrastructure that can attract companies, capital, and talent will be much more interesting,” she explains. “Mining and holding Bitcoin can create value for the country, while a regulated ecosystem is what creates an industry around it.”
Building a regulated ecosystem
That distinction is increasingly visible in GMC. The Special Administrative Region has made finance and digital assets one of its core sectors, while the Gelephu Financial Services Office (GFSO) acts as the independent regulator for both traditional finance and blockchain-based activities.
Under the Financial Services Act 2025, firms undertaking regulated financial services in or from GMC require a Financial Services Licence. The framework is supported by rulebooks covering areas including anti-money laundering, conduct of business, funds, prudential requirements, and market infrastructure, alongside specific virtual asset guidance.
For institutional participants, the significance lies less in whether digital assets are permitted and more in whether the surrounding infrastructure resembles the operating environment they already expect in conventional markets.
“Institutions will look beyond whether digital assets are permitted and ask whether the market can support capital at scale,” Chen says. “That means reliable custody, deep liquidity, efficient settlement, banking and fiat rails, clear asset segregation, strong AML controls, and reporting that meets institutional requirements.”
Custody as a foundation
Custody is already becoming one of the clearest building blocks. The GFSO’s financial institutions directory lists a number of active firms authorised to provide custody alongside other regulated activities, including Matrix Gelephu, Ceffu Digital, KairosX Gelephu, 8020 Finance, and BTSE Exchange. The latter is also authorised to operate a multilateral trading facility. A functioning institutional market requires more than a trading venue. It needs regulated counterparties, arrangements for safeguarding assets, access to banking, liquidity, risk controls, and an operating model capable of supporting assets throughout their lifecycle.
For Chen, predictability will be fundamental if GMC is to move from attracting firms to attracting institutional capital.
“The biggest requirement is predictability. Institutions need clear rules, credible supervision, reliable counterparties, and confidence that those standards will remain understandable as the market develops.
“They also need the operational infrastructure they already expect in traditional finance, from custody and settlement to risk management, reporting, and compliance.”
The licensing process is designed to require more than a nominal presence. According to the GFSO, firms receiving in-principle approval must satisfy conditions before receiving a full licence, including incorporating in GMC, opening a local bank account, injecting the required regulatory capital, securing office space, and hiring key personnel.
That emphasis on substance is relevant as more international digital asset businesses consider the jurisdiction. Bitget signed a cooperation agreement with the Gelephu Mindfulness City Authority in August, setting out a framework for the exchange to establish a legal presence, prepare an application for the relevant Financial Services Licence, and work with the authority on regulatory, operational, and ecosystem development.
For GMC, however, the larger question is whether new entrants create an interconnected institutional market rather than a collection of separately licensed businesses.
Designing for convergence
There may be an advantage in constructing that market from the ground up. Established financial centres are adapting legacy banking, securities, and post-trade infrastructure to accommodate blockchain-based assets. GMC has the opportunity to design parts of its architecture with traditional securities, virtual assets, and tokenised instruments in view at the same time.
“There is a real advantage in being able to design for convergence from the beginning,” Chen informs.
“Many established financial centres are integrating digital assets into systems that were built decades before blockchain existed. GMC has an opportunity to think about banking, digital assets, tokenised securities, custody, and settlement as parts of the same financial architecture from the outset.”
This convergence could ultimately prove more significant to the asset servicing industry than Bitcoin itself. The GFSO framework allows regulated activities to be carried out in relation to traditional assets, such as securities, as well as virtual assets. In principle, that creates room for service providers to develop models spanning conventional investment products and digitally native instruments rather than building parallel infrastructures.
Tokenisation enters the picture
Tokenisation is likely to be an important test. As asset managers and market infrastructures explore tokenised funds, bonds, and other real-world assets, jurisdictions are increasingly being judged not simply on their treatment of cryptocurrencies but on whether their legal, custody, and settlement frameworks can support securities represented on distributed ledgers. Chen expects cryptocurrencies and tokenised assets to play different roles in Bhutan’s development.
“Bitcoin has already been strategically important to Bhutan, while tokenisation could broaden the economic opportunity considerably by connecting blockchain infrastructure with securities, funds, and other real-world assets. Over time, some of the biggest opportunities in digital assets could come from bringing existing financial assets onto more programmable and globally accessible infrastructure.”
From infrastructure to economic development
The economic rationale extends beyond attracting financial institutions. Bhutan has linked its digital asset strategy to the development of domestic expertise and employment.
Reuters reported that the country is training young people in blockchain and AI as it seeks to address the outward migration of skilled workers. GMC’s Bitcoin Development Pledge similarly connects digital assets with creating skilled employment and developing capabilities in technology, finance, and clean industries.
The test is execution
The challenge now is execution. A regulatory framework, licences, and cooperation agreements can establish the foundations of a market, but they do not by themselves create liquidity, institutional flows, or an established post-trade ecosystem. GMC will need to demonstrate that licensed firms are conducting substantive business; that institutional capital can move efficiently through the market; and that custody, settlement, banking, and compliance arrangements can operate at scale. Chen says those are the measures by which the project should ultimately be assessed.
“The clearest indicator will be what gets built around the assets. I would look at the number and quality of regulated financial institutions establishing substantive operations in GMC, institutional capital being deployed, liquidity, and transaction activity, locally created jobs and expertise, and whether companies are building businesses there rather than simply obtaining licences.”
Bhutan has already demonstrated that renewable energy can be converted into a sovereign digital asset position. The more consequential experiment now underway in Gelephu is whether that position can provide the foundation for a durable institutional financial market.
As Chen concludes: “Ultimately, success would mean Bhutan is known for the financial ecosystem it has created around digital assets, rather than primarily for the Bitcoin it holds.”
NO FEE, NO RISK
100% ON RETURNS If you invest in only one asset servicing news source this year, make sure it is your free subscription to Asset Servicing Times
100% ON RETURNS If you invest in only one asset servicing news source this year, make sure it is your free subscription to Asset Servicing Times