What the future holds
16 Sep 2026
As wealth and asset managers contend with ageing technology, private-market complexity, and the rise of AI, Russell Andrews of FIS tells Zarah Choudhary why the industry’s next phase of transformation will depend as much on data and operating-model redesign as it does on new technology
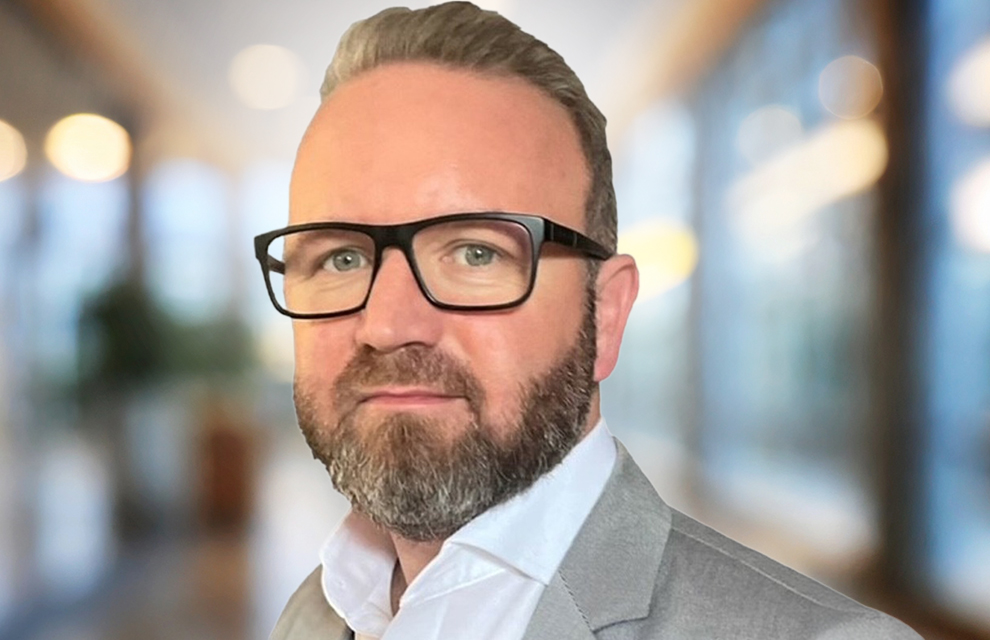 Image: FIS
The operating model behind wealth and asset management is being asked to do far more than simply process transactions efficiently. As firms expand into new asset classes, face greater pressure on resilience, and attempt to make practical use of AI, the focus is shifting from cutting costs to building infrastructure capable of supporting growth.
That is the view of Russell Andrews, head of wealth and asset management vertical, capital markets at FIS, who says firms are increasingly reassessing the technology, data, and operating structures underpinning their businesses.
Andrews has spent 26 years in the industry, including the past three at FIS. His current role involves working with clients on strategic and operational challenges and considering how technology can support a more interoperable ecosystem.
“The agenda has moved away from traditional cost reduction and efficient operations,” Andrews informs. “Firms still need efficiency, of course, but the bigger priority today is creating an operating model that can support growth, product innovation, and more demanding clients without increasing operational risk.”
In practical terms, operations can no longer be viewed as a back office cost centre detached from commercial strategy. Andrews argues that every part of the organisation is now expected to contribute to growth.
He identifies four areas driving that change: scalability, resilience, data, and the widening investment universe.
Managers want to launch products and enter markets faster without continually adding people and infrastructure. At the same time, operational resilience, cybersecurity, and regulatory change have moved firmly onto the board agenda.
Data has also become a strategic asset rather than simply an operational input. Managers increasingly require timely and reliable information to support investment decisions, risk management, and client reporting.
The fourth pressure comes from the assets themselves. Private markets, alternatives, direct indexing, and hybrid products are forcing firms to support structures and workflows that many traditional platforms were not designed to handle.
“We used to hear firms say ‘how do we run the business more cheaply?’” Andrews says. “Now what we hear is: ‘how do we build an operating model capable of supporting tomorrow’s business rather than just worrying about today?’”
Legacy systems remain difficult to dislodge
That ambition does not mean the industry is rapidly removing decades-old infrastructure.
According to Andrews, most firms are pursuing a mixture of replacement and coexistence, with full platform migrations remaining difficult because legacy systems often contain decades of embedded data, business logic, and customisation.
Although those systems may be inefficient, they can remain deeply connected to day-to-day operations and often still function well enough to make wholesale replacement difficult to justify.
As a result, firms have frequently modernised around the core rather than replacing it, adding cloud services, workflow tools, APIs, and orchestration layers.
The approach can generate short-term gains, but Andrews warns that it can also create another problem.
“By simply adding new technology around an ageing core, what you are actually doing is creating a much more sophisticated level of technical debt rather than removing it,” he explains.
More progressive firms, he adds, are taking a phased approach, identifying unnecessary customisation, removing duplicated functionality, and gradually moving processes onto more modern, modular, and integrated platforms.
Without a clear target architecture, firms risk entering what Andrews describes as a permanent strategy of “tinkering around the edges”, where the technology estate appears modern at the surface while manual intervention and reconciliation remain embedded underneath.
AI moves from hype to workflow
AI is becoming one of the main forces pushing firms to confront those underlying weaknesses.
Andrews is sceptical that the immediate value of AI will come from autonomous investment management. Instead, he sees the clearest near-term opportunities in reducing the operational work involved in finding information, interpreting unstructured data, investigating exceptions, and moving workflows between systems. Exception management is one example. AI can be used to identify likely causes of reconciliation breaks, settlement failures, or cash discrepancies, and recommend the next action.
Client onboarding and servicing is another. Tools can extract and validate information from documents and support Know Your Customer (KYC), account-opening, and suitability processes.
Compliance teams are also exploring AI for interpreting regulation, reviewing restrictions, monitoring communications, and investigating potential breaches. For private markets, where information is frequently buried in documents rather than delivered through standardised feeds, AI could help extract terms, cash flows, exposures, and obligations from capital notices, and other unstructured material.
Andrews also points to technology delivery as one of the areas where AI has already produced tangible value, particularly through coding, testing, documentation, and technology modernisation. Yet he draws a clear distinction between individual productivity gains and genuine operating-model change.
“A standalone AI chatbot may improve individual productivity, but it will not materially transform the operating model,” he points out.
“The real prize comes when AI can access well-governed data, understand the operational context, and then initiate workflows and operations within defined controls.”
Private markets expose operating-model gaps
The need for that combination of technology and data becomes particularly visible as wealth and asset managers increase their exposure to private markets.
Public-market infrastructure has largely developed around standardisation, electronic feeds, regular pricing, and predictable transaction lifecycles. Private assets work differently.
They often depend on bespoke legal agreements, PDFs, and manager-provided information, while valuations can be less frequent and ownership structures more complex.
Capital calls, distributions, and liquidity management also introduce processes that do not sit naturally within operating models designed for listed securities.
Andrews highlights fragmented and unstructured data, inconsistent asset identifiers, complex ownership structures, liquidity management, and fee calculations among the main operational challenges.
The issue could become more acute if private assets continue to move towards a broader retail investor base. Managers that have historically supported relatively small numbers of institutional investors may need operating models capable of handling much greater volumes.
The answer, Andrews argues, is not to “shoehorn” private assets into systems built for public markets. Firms instead need platforms or ecosystems that can support multiple accounting models and complex ownership structures while retaining a consistent data and control framework.
That challenge feeds directly into another longstanding industry problem: creating a reliable enterprise-wide view of investment and client data.
Over time, firms have accumulated multiple systems, vendors, administrators, and books of record. The same information can therefore be represented differently depending on whether it is being viewed by the front, middle, or back office.
Private assets deepen that fragmentation because much of their information arrives through emails or unstructured documents and must be interpreted before it can enter an enterprise data environment.
Simply putting information into one warehouse does not create a single source of truth, Andrews says.
Firms need common definitions, consistent identifiers, agreed rules around timeliness, and exception management, as well as alignment between accounting, investment, risk, and client-management functions.
“A reliable enterprise view does not mean everything sits in one physical database,” he notes. “It means you need an agreed, governed version of the truth that users and applications can interface with confidently.”
That foundation, he adds, is also essential for AI.
A more selective approach to outsourcing
Technology modernisation is being accompanied by a rethink of where work should sit. The industry has debated insourcing and outsourcing for decades, but Andrews says the decision is becoming less binary. Rather than classifying themselves as an outsourced or in-sourced organisation, managers are increasingly deciding at a function level.
Activities closely linked to client differentiation, proprietary intellectual property, investment decision-making, or the client relationship are more likely to remain in-house.
Standardised and operationally intensive functions, particularly those requiring scale, specialist expertise, or significant technology investment, are stronger candidates for outsourcing.
A third model is also gaining ground: co-sourcing. Under that approach, managers can retain ownership of strategic data, governance, and key decisions while using external partners for scale, specialist capabilities, and operational resources.
Andrews believes the future is likely to involve a blend of retained, co-sourced, and outsourced functions, potentially varying across jurisdictions.
AI as catalyst, not solution
Looking three to five years ahead, Andrews expects the most significant change to come not from AI alone but from the convergence of AI, data, and operating-model transformation.
AI will attract the headlines, he says, but its greater impact may be in forcing firms to resolve long-standing structural weaknesses around fragmented data, manual workflows, and organisational silos.
He expects the industry to move towards AI-led operating models in which agents are embedded into day-to-day operations, identifying exceptions, interpreting unstructured information, and recommending actions within defined controls.
That could begin to alter the economics of the industry. Growth may become less directly tied to headcount, while operations become more predictive, and client service more personalised.
Organisational structures could change with it, with smaller teams supervising AI-enabled workflows rather than manually executing each step.
For firms, however, the technology itself will not decide the outcome.
“AI is the catalyst,” Andrews concludes, “but data and operating-model redesign will really determine who captures the most value.”
NO FEE, NO RISK
100% ON RETURNS If you invest in only one asset servicing news source this year, make sure it is your free subscription to Asset Servicing Times
100% ON RETURNS If you invest in only one asset servicing news source this year, make sure it is your free subscription to Asset Servicing Times